61 days ▼ 31 days since April
For nonprofits
Your finance partner for clarity, governance confidence, and more impact.
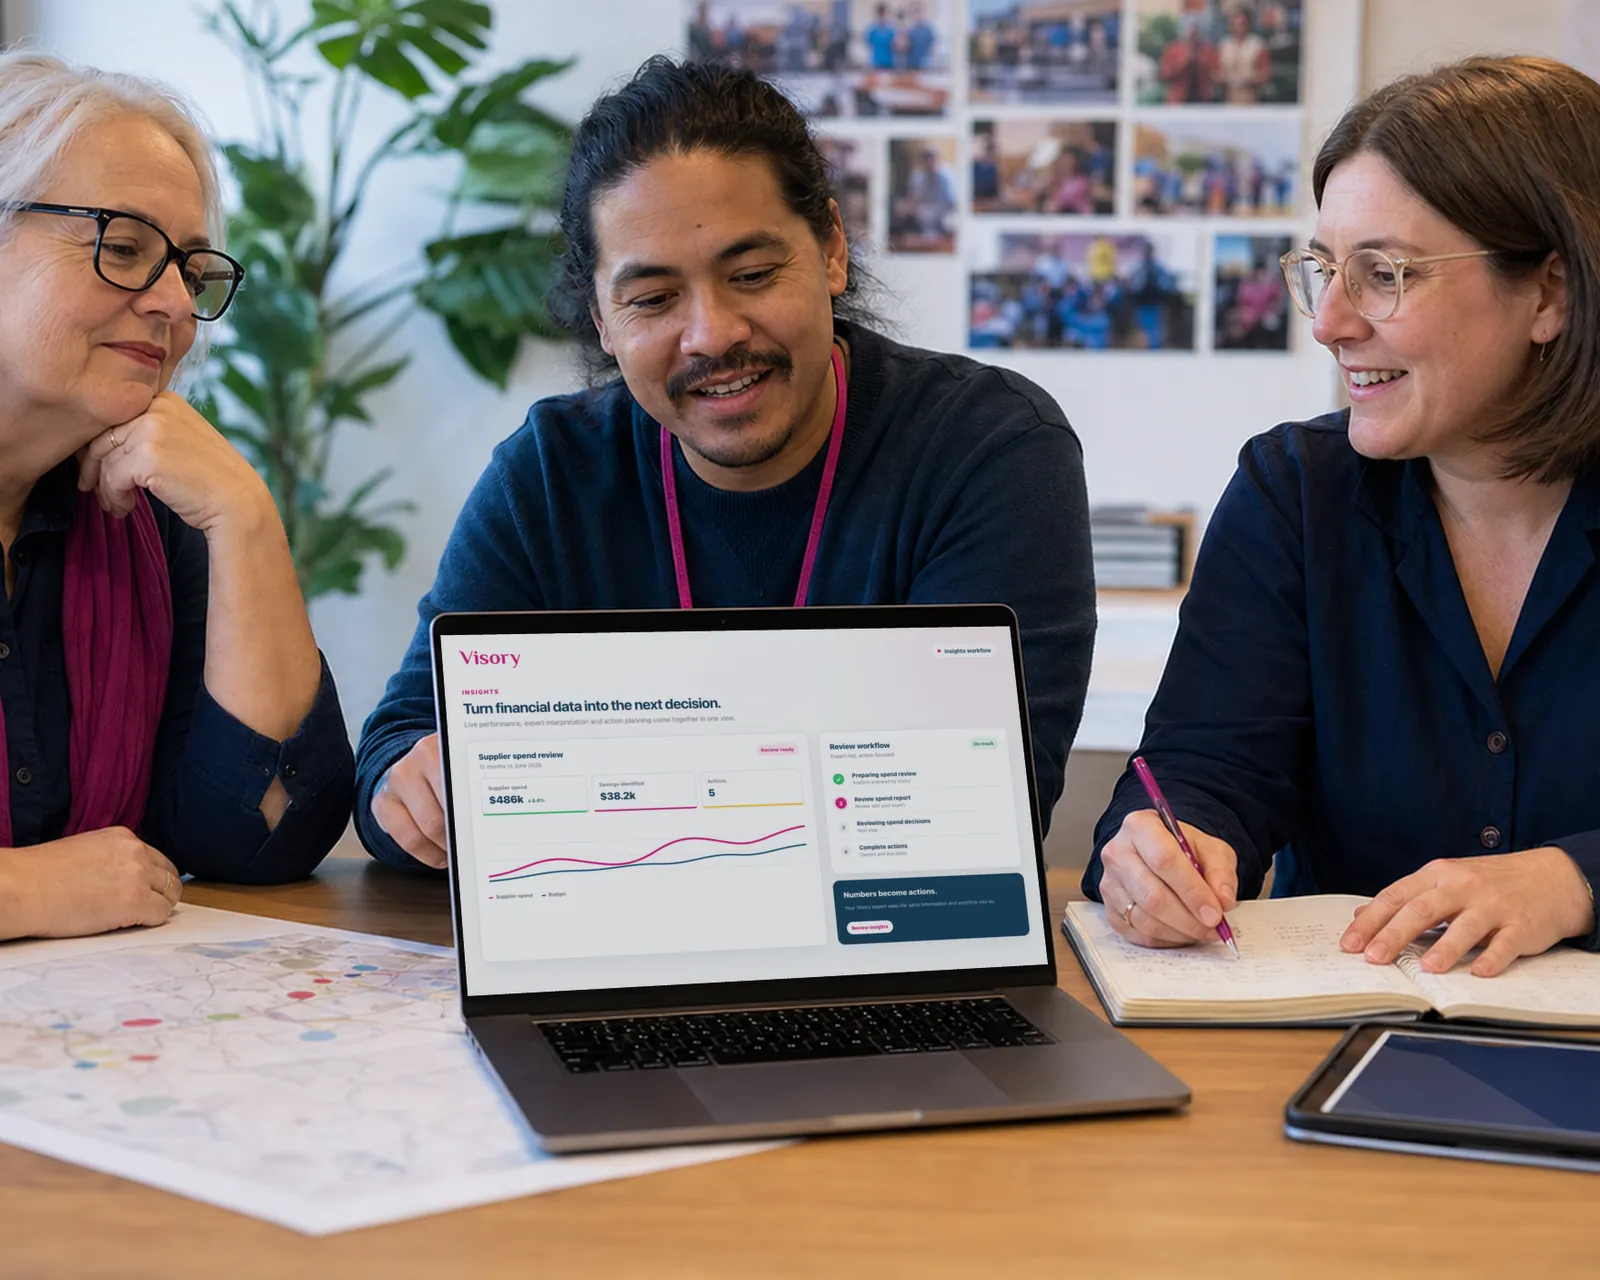
We run your finance function. You get strategic insights. Visory runs bookkeeping, payroll, accounts payable, and accounts receivable for US nonprofits, with a dedicated team who know restricted funds, grant reimbursements, and the Form 990, and Delphi AI under their oversight. Once a month, Organization Performance turns the numbers into a picture your board can act on.
- Every gift and grant tagged by donor, purpose, and restriction the day it lands, so the board sees what is free to spend.
- Expenses coded by program and by function, the split your financial statements and the Form 990 both report.
- Board-ready reporting every month: cash, revenue by source and funder, program performance, and the year ahead, in plain English.
Who we work with
Built for mission-led organizations doing complex work on lean finance.
Several funders, a board of volunteers, restricted gifts, and a finance function that has never been resourced to match. That is who Visory is built for.
- 5 to 100 staff and roughly $750k to $20m in revenue, led by an executive director or CEO who answers to a board.
- Revenue from government grants and contracts, foundations, individual donors, and earned income, each with its own timing and conditions.
- Gifts and grants that come with donor restrictions, by purpose or by time.
- A part-time bookkeeper, no dedicated finance person, or a finance director buried in processing.
Anywhere in the United States. Your books stay in your own QuickBooks or Xero file, which you own, and your dedicated team works inside it.
The pressure
Four rules shape your year. Your funders and regulators set them.
Grants arrive on the funder’s schedule, programs cost money every week, and the board, the auditor, and the regulators all want the same numbers told three ways. The finance function is where that gets managed, or missed.
Growth moves you to a longer return.
The books are kept in the shape the return draws on all year, by program and by function, so its numbers are a report, not a rebuild.
Set by Internal Revenue Code section 6033; Form 990 series
Most tax-exempt organizations file an annual return: Form 990-N if gross receipts are normally $50,000 or less, Form 990-EZ or Form 990 if gross receipts are under $200,000 and total assets under $500,000, and Form 990 above that. Private foundations file Form 990-PF. The return is due by the 15th day of the fifth month after the year ends, with an automatic six-month extension on Form 8868, and an organization that does not file for three consecutive years automatically loses its exemption.
Internal Revenue Code section 6033, and section 6033(j) on automatic revocation; IRS, Form 990 series: which forms do exempt organizations file?; IRS, Annual exempt organization return: due date; IRS, Automatic revocation of exemption; pages reviewed June 28, 2026.Sources IRS: Which Form 990 to file IRS: Return due date IRS: Automatic revocation
Every federal dollar has to trace back to its award.
Spending is coded by award and program as it happens, including money that reaches you through a state or county, so the figures your auditor tests come from the ledger.
Set by 2 CFR 200.501
A non-Federal entity, which includes a nonprofit, that expends $1,000,000 or more in Federal awards during its fiscal year has a single audit for that year, or in limited cases a program-specific audit. Awards it spends as a subrecipient, such as federal money passed through a state or county, count too. Below $1,000,000 it is exempt from Federal audit requirements for that year, but its records stay available for review or audit by the Federal agency, the pass-through entity, and the Government Accountability Office.
2 CFR 200.501(a), (b), (e), and (g), as amended by 89 FR 30046, effective October 1, 2024.Revenue decides how much assurance the report needs.
Revenue and support are coded by source as they land, so the size of the year is known long before the report is due, and the auditor or reviewer works from books that are already closed.
Set by New York Executive Law sections 172 and 172-b
A charitable organization that intends to solicit contributions from people in New York, or from a governmental agency, files a registration with the Attorney General before any solicitation, unless an exemption applies. Each year it files a financial report by the fifteenth day of the fifth month after its fiscal year ends: with audited financial statements when gross revenue and support exceed $1 million, and with a review report from $250,000 to $1 million. Other states set their own registration rules.
New York Executive Law section 172(1) and section 172-b(1) and (2), as published by the New York State Senate.Sources New York Senate: Executive Law 172 New York Senate: Executive Law 172-b
Cash in the bank is not all yours to spend.
Gifts and grants are tagged by donor, purpose, and restriction as they arrive, and releases are recorded as the money is spent, so the board sees what is free to use.
Set by FASB ASC 958; Form 990, Parts IX and X
Under US GAAP, a nonprofit presents two classes of net assets: with donor restrictions and without donor restrictions. A gift a donor restricts by purpose or time stays in the first class until the restriction is met, then is released to the second. An organization that follows ASC 958 reports the same two classes on the Form 990 balance sheet, and section 501(c)(3) and 501(c)(4) organizations split their expenses between program services, management and general, and fundraising.
Financial Accounting Standards Board, ASU 2016-14, Not-for-Profit Entities (Topic 958): Presentation of Financial Statements of Not-for-Profit Entities, effective for fiscal years beginning after December 15, 2017; IRS, 2025 Instructions for Form 990, Part IX (statement of functional expenses) and Part X (balance sheet), lines 27 and 28.Every instrument named here is listed with its effective date at the foot of this page.
What the board sees each month
Four numbers, closed and explained before the meeting.
Revenue, year to date $1.24m ▲ 1% ahead of budget By source: grants, contracts, gifts, earned income
Days of cash on hand 61 days ▼ below the 90-day target Days of expenses covered by cash without donor restrictions
Program services 84% Of total expenses Program, management and general, and fundraising
Net assets with donor restrictions $1.6m Tracked by donor Released as each restriction is met
How would your last board meeting have gone with these four numbers in hand? Start with a discovery call. A senior member of the Visory team then runs the free financial health check on your own numbers, before anything is agreed.
Book a discovery callWhat we run for nonprofits
From accurate processing to leadership confidence.
Organization Performance leads. The basics underneath it make it trustworthy and free your team for the work that matters, run by a dedicated team with Delphi AI under their oversight.Flat monthly fee. No hourly billing.
- 1 Accurate processing Bookkeeping and payroll done right, every month.
- 2 Clean, reliable data The foundation that makes reporting defensible.
- 3 Meaningful insights Cash, revenue sources, programs, the year ahead.
- 4 Leadership confidence The executive director presents numbers they trust. The board backs the plan.
The leading service
Organization Performance
A monthly read on the organization, closed on your timetable and briefed by your Business Performance Partner: revenue by source and funder, days of cash on hand, program performance, restricted funds, and the year ahead. Board-ready, in plain English, with one move to make.
See how Organization Performance works- Monthly board-ready report
- Structured session with your executive director and treasurer
- Twelve-month forward view of cash and funding
- A named Business Performance Partner
The basics underneath it
Bookkeeping
Grants, gifts, and earned income tracked by source, funder, and program, with donor restrictions kept visible and expenses coded by function.
Explore bookkeepingPayroll
Pay runs owned by a Payroll Specialist and checked by Delphi AI, staff time allocated across programs and grants, and payroll tax filings prepared from the same run.
See how payroll runsAccounts payable
Supplier bills captured, coded to the right program and grant, and paid when you say so.
See accounts payableAccounts receivable
Grant reimbursement requests and contract invoices raised on schedule and followed up in your name.
See accounts receivableThe Form 990, state registration, tax advice, and the audit stay with your organization, its tax advisor, and its auditor. Visory keeps the books ready for all of them, all year, and runs the bookkeeping, payroll, payables, and receivables behind them.
Organization Performance
One month of Organization Performance, start to finish.
Reports tell you what happened. Organization Performance tells you what it means, and what to do about it. Here is September for Riverbend Community Alliance, a fictional community services nonprofit with about $4.9m in annual expenses, 45 staff, and five funders.
Programs are on budget. The gap is timing. $380k of government grant reimbursements has been billed and not yet paid.
Grant reimbursements unpaid $380k At Risk $230k past the $150k the organization carries in a normal month: two requests are held waiting on the program reports that go with them
Days of cash on hand Collecting the $230k adds about 17 days of operating expenses to unrestricted cash
File the two program reports this month so the held reimbursements are released, and bill both agencies monthly from October. The reports’ financial figures are drafted from the program ledgers and ready for your sign-off at the session.
≈ +17 days of cash Insight session Accepted 9:00 to 9:45am · Video call  With your Business Performance Partner
Prepared by Delphi AI, briefed by your Business Performance Partner, in plain English, ready to take to the board. No jargon. No guesswork.
- Monthly board-ready report
- Structured insight sessions
- Cash, revenue sources, and programs, twelve months out
See this on your own numbers. A discovery call is a conversation about your funders, your programs, and what you want your board to see each month.
Book a discovery callFits your stack
Works with the tools you already use.
Your ledger and your payroll stay where they are. Visory connects to them and keeps the data flowing every day, so your team and Delphi are working from current numbers.
Accounting and books
Where your ledger and reporting live.
Payroll and people
Pay runs, payroll tax withholding and filings, and the people behind them.
Funders, grants, and donors
Grant and gift income tracked by funder, program, and restriction in your ledger, with reimbursement requests and funder reports drawn from it.
Resources for nonprofits
Content written for nonprofits by the expert teams at Visory.
Common questions
Straight answers for nonprofits.
The questions executive directors and boards ask before they hand Visory the finance function. The general ones are on the common questions page.
We already have a finance director. Where does Visory fit?
Underneath them. Visory runs the processing: bookkeeping, payroll, payables, receivables, and the monthly close. That frees your finance director to interpret the numbers, advise the executive director, and work with the board. With clean, timely data underneath them, they do the work only they can do.
We already have a bookkeeper. What changes?
A bookkeeper records what happened. Visory records it, checks it, and tells you what it means: revenue by source and funder, donor restrictions kept visible, payroll run by a Payroll Specialist, and a monthly report your board can act on. The question is less whether you have a bookkeeper than whether the books produce anything useful beyond compliance.
Can you track restricted funds and support our grant reimbursements?
Yes. Every gift and grant is tagged by donor, purpose, and restriction from the day it lands, and costs are allocated to the programs and grants that incurred them. Money held for a purpose or a period stays with donor restrictions until the condition is met, then is released. When a reimbursement request or a funder report is due, its financial figures come straight from the ledger, so it is drafted rather than rebuilt.
Can you run payroll across our programs and grants?
Yes. A Payroll Specialist runs every pay cycle, with each person’s time allocated to the programs and grants it served, so payroll costs land where your funders and the Form 990 expect them. Delphi AI prepares and checks the run, your Payroll Specialist oversees it, you approve it, and it is paid, with payroll tax filings prepared from the same run.
What does the board see each month, and when?
The month is closed on a timetable agreed with you and set to your board calendar. Then a short, plain-English report: cash on hand, revenue by source and funder, program performance against budget, net assets with donor restrictions, and a forward view of cash twelve months out. Your Business Performance Partner walks the executive director and treasurer through it before the meeting, so the board conversation is about the plan, not the numbers.
Does Visory prepare our Form 990?
Visory keeps the books ready for it all year: revenue, expenses by program and by function, and balances in the shape the return draws on, with records your tax advisor and auditor can work from without a catch-up. Preparing and signing the return, and any state charitable registration or annual report, stays with your organization and its tax advisor.
Do we need a Single Audit?
A nonprofit that spends $1,000,000 or more in federal awards in its fiscal year, including federal money received through a state or county, is generally required to have a single audit, or in some cases a program-specific audit, under the threshold that took effect on October 1, 2024. Visory keeps federal award spending coded by award and program, so the figures your auditor tests come from the ledger. Whether the requirement applies is a question for your auditor.
Are we too small for this?
Usually not. Several funders, restricted gifts, grant reimbursements, and board reporting do not shrink with the organization, and the cost of getting them wrong is proportionally higher. Visory works best from around five paid staff; below that, with no paid employees at all, it is usually more than you need.
How much does Visory cost?
Visory charges one flat monthly fee for the scope we agree. No timesheets, no hourly billing, no surprises. The fee reflects the services you take and the volume of work in your organization, so you know the monthly cost before you start.
See how pricing works More questions, longer answers. Every question has its own link. See all common questions
General information for nonprofits, not financial or tax advice.
Getting started
Start with clarity, not a contract.
Three steps, in whatever rhythm suits you. Each one is useful on its own.
-
Book a discovery call
An obligation-free conversation about your mission, your funders, and what you want the numbers to tell you.
Obligation-free -
Get your free financial health check
A senior member of the Visory team analyzes your financials and shows where your finance function can improve. See the clarity before you commit to anything.
Free · your own numbers -
See how Visory works in practice
A walkthrough of the finance function and Insights working together on an organization like yours. If it fits, we agree a flat monthly scope.
Flat monthly fee
Get started
Walk into your next board meeting with the numbers behind you.
Start with a discovery call. Then a senior member of the Visory team analyzes your numbers, free of charge, and shows you where the finance function can improve.
Sources (5) · rules last checked October 9, 2026
- Internal Revenue Code section 6033; IRS, Form 990 series: which forms do exempt organizations file? (Form 990-N for gross receipts normally $50,000 or less; Form 990-EZ or 990 for gross receipts under $200,000 and total assets under $500,000; Form 990-PF for private foundations); IRS, Annual exempt organization return: due date, the 15th day of the fifth month after the end of the accounting period, with an automatic six-month extension on Form 8868; pages reviewed June 28, 2026.
- Internal Revenue Code section 6033(j); IRS, Automatic revocation of exemption: organizations that do not file for three consecutive years automatically lose their tax-exempt status, page reviewed June 28, 2026.
- 2 CFR 200.501(a), (b), (e), and (g): a single or program-specific audit for a non-Federal entity that expends $1,000,000 or more in Federal awards in its fiscal year, as a recipient or a subrecipient, and records available for review below that threshold; as amended by 89 FR 30046, effective October 1, 2024.
- New York Executive Law section 172(1): registration with the Attorney General before any solicitation; section 172-b(1) and (2): annual financial report by the fifteenth day of the fifth calendar month after the close of the fiscal year, with an audit report above $1 million in gross revenue and support and a review report from $250,000 to $1 million; as published by the New York State Senate.
- Financial Accounting Standards Board, ASU 2016-14, Not-for-Profit Entities (Topic 958): net assets with donor restrictions and without donor restrictions, and the analysis of expenses by function and nature; effective for fiscal years beginning after December 15, 2017. IRS, 2025 Instructions for Form 990: Part IX, statement of functional expenses, and Part X, balance sheet, lines 27 and 28 for organizations that follow ASC 958.